Score-based confidence intervals and hypothesis tests for variances and covariances of random effects in linear mixed models fitted with lme4.
reconf computes confidence intervals and score tests for
the variances and covariances of random effects in linear mixed models.
The intervals invert a profile score statistic on the
variance-covariance scale, with nuisance parameters estimated on an
extended parameter set. The intervals have near-nominal coverage, even
near the boundary of the parameter space where Wald and likelihood ratio
intervals can be unreliable; see the references.
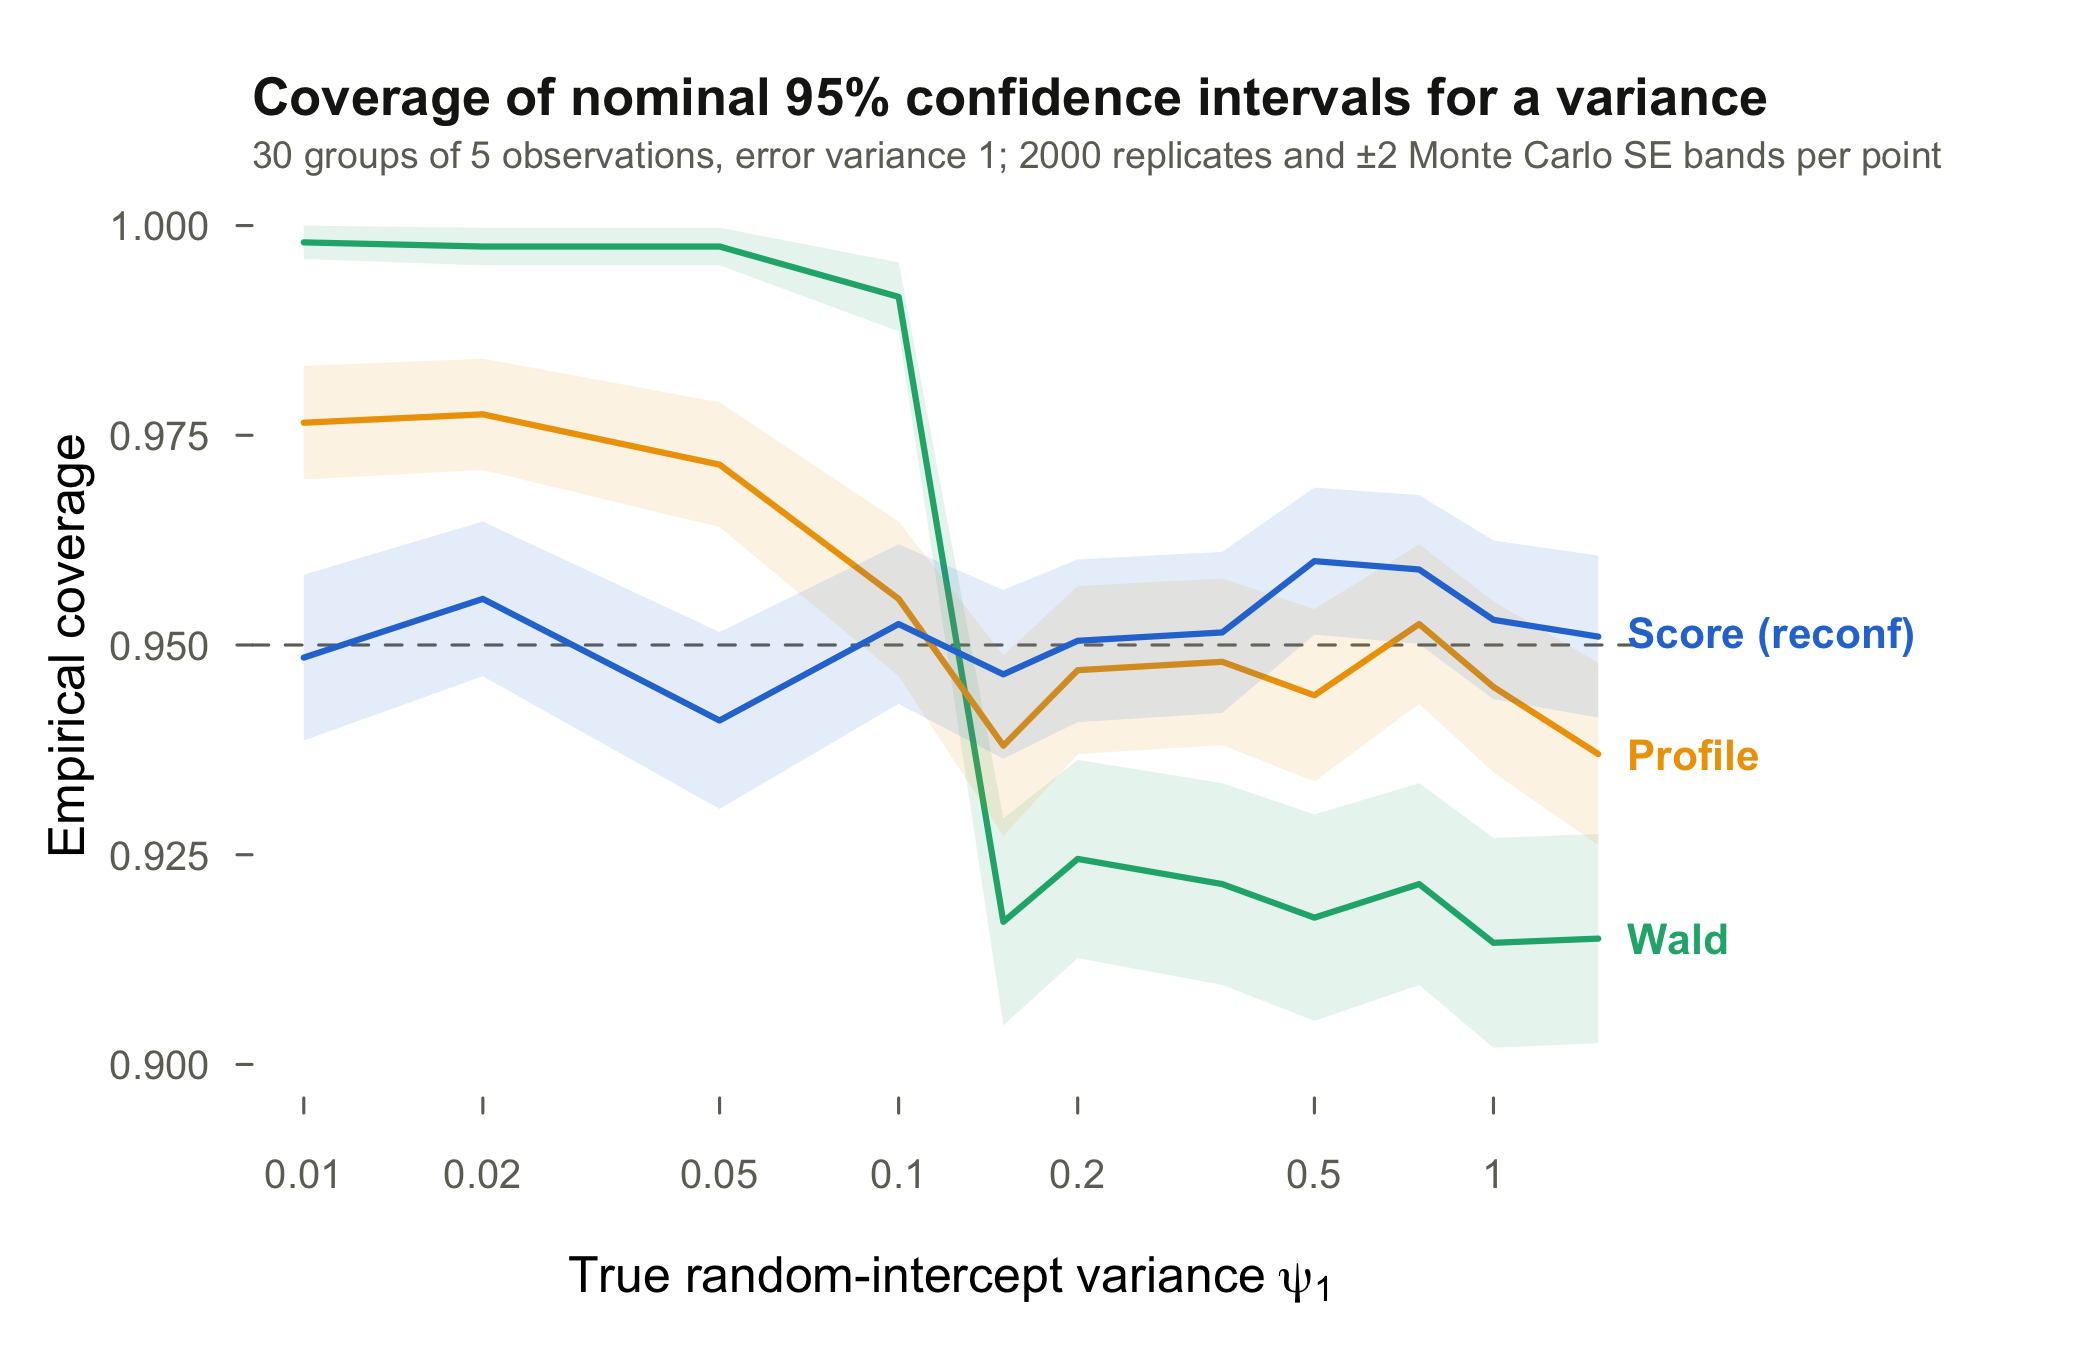
The figure shows the estimated coverage of 95% intervals for a
random-intercept variance, with 30 groups of 5 observations and 2000
replicates at each of eleven values of the variance. Across those
values, the coverage was between 0.941 and 0.960 for the score
intervals, between 0.914 and 0.998 for Wald intervals, and between 0.937
and 0.978 for profile likelihood intervals; the Monte Carlo standard
errors are at most 0.0063. The simulation is
coverage_simulation.R in the scripts
folder of the repository.
On the FEV1 model of the vignette, vc_ci() computed the
four intervals in 0.7 s and
confint(fit, method = "profile") in 28 s, in one run on a
laptop.
install.packages("reconf")

# Development version
remotes::install_github("koekvall/reconf")library(lme4)
library(reconf)
# Fit a linear mixed model
fit <- lmer(Reaction ~ Days + (Days | Subject), data = sleepstudy)
# 95% score-based CIs for all covariance parameters, residual variance included
vc_ci(fit)
# CI for selected parameters, by name or index
vc_ci(fit, parm = "var_(Intercept)|Subject")
# Score test that the random slope variance (index 3) is zero
vc_test(fit, parm = 3)
# Score test that all random-effect covariance parameters are zero
vc_test(fit)
# Build the model once to reuse its precomputation across calls
m <- vc_model(fit)
vc_ci(m, parm = 3)
# Log-likelihood, score, and information at any covariance parameters
ll <- vc_loglik(fit)
ll(c(600, 10, 35, 650))The parameter ordering follows
as.data.frame(VarCorr(fit), order = "lower.tri"), with the
residual variance last.
varcomp
(formerly lmmvar)
implements the method of Zhang, Ekvall, and Molstad (2025) for a model
with one variance component and an error term, with the proportion of
variability (heritability) as the parameter of interest.
reconf instead treats the variances and covariances
themselves as the parameters of interest and covers all covariance
parameters in models fitted with lme4.